How it works
The cash flow is the list of money in and out by year. Write that list first.
- List the cash you pay or receive in each year of the term.
- Subtract credits in the year they actually happen.
- Pick one discount rate and keep it visible.
- Shrink each later year. Add the year values. That sum is NPV.
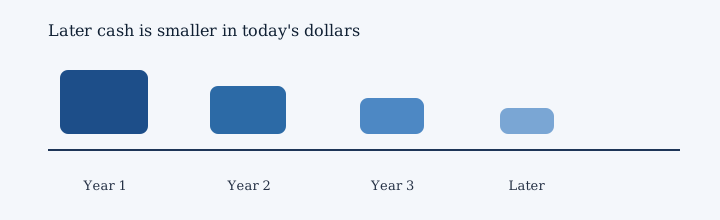
Formula in words. NPV = year 1 cash / (1 + rate) + year 2 cash / (1 + rate)^2 + later years in the same way.
| Input | Meaning |
|---|---|
| Start rent | The first-year rent before extras |
| Term | How many years the lease runs |
| CAM and other extras | Shared building cost, tax, and insurance if the tenant pays them |
| Credits | Free rent and tenant improvement money |
| Discount rate | How hard you shrink later cash |
Worked example
Here is a teaching sample. It is not customer data and not a result from a live client.
| Metric | Lease A | Lease B |
|---|---|---|
| Start rent | $42,000 | $39,060 |
| Year-1 extras | $8,400 | $8,988 |
| Year-1 credit | $18,000 | $9,900 |
| Sample NPV | $363,861 | $353,604 |
| Year | Rent | Extras | Credit | Cash out | Value today |
|---|---|---|---|---|---|
| Year 1 | $42,000 | $8,400 | $18,000 | $32,400 | $30,000 |
| Year 2 | $43,260 | $8,652 | $0 | $51,912 | $44,506 |
| Year 3 | $44,558 | $8,912 | $0 | $53,470 | $42,446 |
| Year 4 | $45,895 | $9,179 | $0 | $55,074 | $40,481 |
| Year 5 | $47,271 | $9,454 | $0 | $56,725 | $38,606 |
| Year 6 | $48,689 | $9,738 | $0 | $58,427 | $36,819 |
| Year 7 | $50,150 | $10,030 | $0 | $60,180 | $35,114 |
| Year 8 | $51,655 | $10,331 | $0 | $61,986 | $33,489 |
| Year 9 | $53,205 | $10,641 | $0 | $63,846 | $31,939 |
| Year 10 | $54,801 | $10,960 | $0 | $65,761 | $30,460 |
| Sample NPV | — | — | — | — | $363,861 |
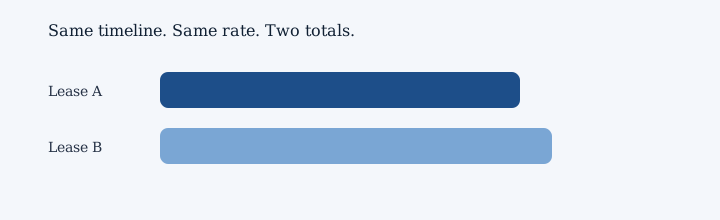
How to read the sample
Sample NPV for Lease A sample is about $363,861. A second path lands near $353,604. That gap is a talking point, not a promise.
Free rent and a build-out check land here. If one path wins only because a credit sat in the wrong year, start over.
Year notes for Lease A sample
- Year 1 of Lease A sample has rent of $42,000.
- Shared building cost is $8,400.
- A credit of $18,000 lowers the cash you pay that year.
- Cash out this year is about $32,400. Free rent and a build-out check land here.
- Later cash gets a shrink for time. At 8 percent, year 1 is worth about $30,000 today.
- Next, year 2 rent is $43,260.
- CAM, which is a shared building cost, is $8,652.
- There is no credit in this year.
- You pay about $51,912 this year after extras and credits. Rent steps up and the credit is gone.
- Time shrinks later cash. At 8 percent, year 2 is worth about $44,506 today.
- Then year 3 rent is $44,558.
- Extras for the building come to $8,912.
- Credits skip this year.
- The net cash this year is about $53,470. The step-up is still small, but it compounds.
- Waiting has a price. At 8 percent, year 3 is worth about $42,446 today.
- After that, year 4 rent is $45,895.
- The shared building cost this time is $9,179.
- No extra credit shows up this year.
- Cash out this year is about $55,074. Later cash is worth less today than year-one cash.
- Later cash gets a shrink for time. At 8 percent, year 4 is worth about $40,481 today.
- In year 5 of Lease A sample, rent is $47,271.
- Shared building cost is $9,454.
- There is no credit in this year.
- You pay about $56,725 this year after extras and credits. This last year still counts. Do not drop it.
- Time shrinks later cash. At 8 percent, year 5 is worth about $38,606 today.
- Year 6 of Lease A sample has rent of $48,689.
- CAM, which is a shared building cost, is $9,738.
- Credits skip this year.
- The net cash this year is about $58,427. Keep this later year in the sum for the sample.
- Waiting has a price. At 8 percent, year 6 is worth about $36,819 today.
- Next, year 7 rent is $50,150.
- Extras for the building come to $10,030.
- No extra credit shows up this year.
- Cash out this year is about $60,180. The row still belongs in the sum for the long path.
- Later cash gets a shrink for time. At 8 percent, year 7 is worth about $35,114 today.
- Then year 8 rent is $51,655.
- The shared building cost this time is $10,331.
- There is no credit in this year.
- You pay about $61,986 this year after extras and credits. Keep this later year in the sum for the long path.
- Time shrinks later cash. At 8 percent, year 8 is worth about $33,489 today.
- After that, year 9 rent is $53,205.
- Shared building cost is $10,641.
- Credits skip this year.
- The net cash this year is about $63,846. The row still belongs in the sum for the long path.
- Waiting has a price. At 8 percent, year 9 is worth about $31,939 today.
- In year 10 of Lease A sample, rent is $54,801.
- CAM, which is a shared building cost, is $10,960.
- No extra credit shows up this year.
- Cash out this year is about $65,761. Keep this later year in the sum for the long path.
- Later cash gets a shrink for time. At 8 percent, year 10 is worth about $30,460 today.
Add those year values. The sample NPV for Lease A sample is about $363,861. This is a teaching sample, not a client result.
Questions this topic answers
These are the standalone authority pages in this family. They are grouped so a reader can start, calculate, compare, or go deeper without a wall of cards.
Start here
Compare options
Common mistakes
For your role
Trusted sources
These are public references. They are not endorsements and not client results.
How to use this with OccupancyNPV
This page answers the concept. OccupancyNPV applies it inside a DealWorkspace: enter lease scenarios, review cash-flow and occupancy cost, then compare NPV and discount-rate sensitivity. OccupancyNPV NPV is not the same as a face-rent comparison. OccupancyNPV is not a CRM or lease-administration suite, and this page is not legal or investment advice.
Next: start the 3-day free trial, open pricing, or continue through related product paths.
How should a tenant treat CAM in the first operating year?